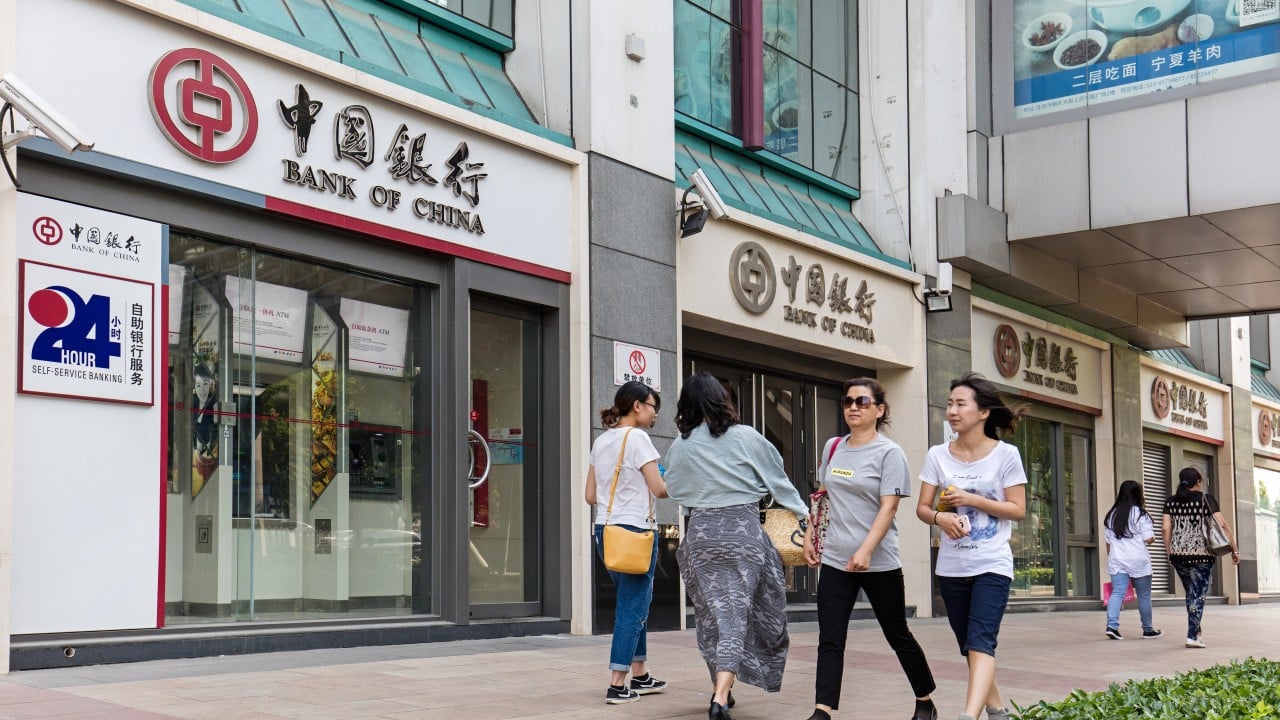
Chinese banks embrace cheaper short-term loan rates despite margin risks
Source: SCMP — Business & Markets
As some major lenders begin pricing corporate debt against flexible short-term markets, analysts warn the shift could squeeze net interest margins even further Chinese commercial banks have begun pricing corporate loans against a short-term interbank repo rate rather than the benchmark loan prime rate (LPR), a shift drawing sharp scrutiny from investors worried about the sector’s already thin profitability. The industry’s average net interest margin – the spread between what banks earn on loans and pay out on deposits – slid to a record low of nearly 1.4 per cent in the first quarter, according to official data. That was well below the 1.8 per cent threshold long regarded by regulators as necessary for healthy, self-funded capital growth. Market observers noted that broader adoption of market-linked pricing could put further pressure on margins in the near term, even as it promises to improve interest-rate risk management over time. Under the new approach, loans are pegged to the depository institutional repo rate (DR), specifically overnight and seven-day interbank rates. These short-term borrowing benchmarks reflect the actual cost of funds that commercial banks charge one another in the open market.
Comments
İlk yorumu siz yazın!